Marine Insurance Fundamentals for Procurement Teams: P&I, H&M and How They Affect Supply Decisions
Marine insurance is not only a finance or legal topic. For procurement managers, ship managers and technical superintendents, insurance directly affects supplier selection, contract terms, documentation requirements, delivery planning and claim handling.
When a spare part is damaged in transit, when a technical item fails after installation, when provisions create a crew welfare issue or when a supplier’s delivery causes operational disruption, the procurement trail becomes part of the insurance discussion.
The most important point for procurement teams is simple: insurance does not replace good purchasing practice. It supports risk management, but buyers still need clear specifications, reliable suppliers, accurate documentation, strong delivery records and well-defined liability clauses.
This article explains the practical basics of P&I, H&M, cargo insurance and supplier liability from a procurement perspective. For broader ship supply support, see Global Ship Supply.
The Three Pillars: H&M, P&I and Cargo Insurance
Marine insurance is usually discussed through several different cover areas. For procurement teams, the three most relevant concepts are Hull & Machinery insurance, Protection & Indemnity insurance and cargo insurance.
Each one addresses a different type of risk. Confusing them can lead to wrong assumptions during supplier negotiations or claim handling.
Hull & Machinery Insurance
Hull & Machinery, often called H&M, generally relates to physical loss of or damage to the vessel’s hull, machinery and installed equipment. It is mainly connected to the vessel as an asset.
From a procurement perspective, H&M may become relevant when purchasing:
- Main engine components
- Auxiliary machinery parts
- Navigation or bridge equipment
- Electrical equipment
- Deck machinery
- Pumps, valves and technical systems
- Repair materials
- Critical replacement parts
However, procurement teams should not assume that every spare part in transit is automatically covered by H&M. Coverage depends on the policy wording, the point of risk transfer, whether the item is installed, the nature of the damage and the insurance arrangement in place.
P&I Insurance
Protection & Indemnity, or P&I, generally relates to third-party liabilities connected to vessel operation. P&I can be relevant to crew, pollution, third-party damage, certain cargo liabilities, illness, injury and operational liabilities.
For procurement teams, P&I becomes important when purchasing items or services that may affect:
- Crew welfare
- Medical response
- Food safety
- Pollution risk
- Port operations
- Third-party exposure
- Operational safety
- Waste handling
- Shipboard services
P&I does not mean every procurement problem is automatically covered. The claim must fit the relevant club rules, policy terms and facts of the incident.
Cargo Insurance
Cargo insurance generally protects goods while they are in transit. For marine procurement, this is highly relevant when spare parts, technical stores, provisions or urgent supplies are being moved from a supplier warehouse to a port, agent, freight forwarder or vessel.
Cargo insurance may be important for:
- High-value spare parts
- Fragile technical equipment
- International shipments
- Air freight and sea freight
- Multi-leg logistics
- Urgent next-port deliveries
- Cross-border procurement
- Temperature-sensitive goods
Procurement teams should clarify who is responsible for insurance during transit, when risk transfers and what documents are needed if damage or loss occurs.
How P&I Clubs Influence Crew, Medical and Operational Supply
P&I clubs are especially relevant when procurement decisions touch crew welfare, medical response, food safety or operational liability. This does not mean the buyer manages insurance directly, but procurement decisions can influence whether a later claim is clear or difficult to support.
Crew Welfare and Provisions
Provisions procurement can create insurance-sensitive situations when food quality, storage, hygiene or documentation becomes an issue. If poor-quality provisions affect crew health, the claim discussion may involve food safety records, supplier details, delivery notes and onboard handling.
Procurement teams should pay attention to:
- Supplier food safety standards
- Product shelf life
- Cold chain requirements
- Delivery temperature records
- Batch information
- Invoice and delivery note accuracy
- Complaint records
- Photos of damaged or poor-quality goods
- Crew feedback after delivery
Good provisions procurement is not only about price. It also protects crew welfare and reduces operational risk.
Medical Supply and Emergency Response
Medical supplies, medicine-related purchases and emergency response items require careful documentation. Procurement teams should ensure the requested items match vessel requirements and that expiry dates, packaging and delivery records are checked.
Key controls may include:
- Product description
- Quantity
- Expiry date
- Storage requirement
- Certificate or compliance document
- Delivery confirmation
- Supplier qualification
- Substitution approval
If the wrong item is supplied or documentation is missing, the problem can become both operational and insurance-sensitive.
Operational Supplies and Third-Party Risk
Some supplies can create third-party exposure if they fail, leak, contaminate, damage property or affect port operations. Examples may include chemicals, hoses, lifting gear, mooring ropes, safety equipment or pollution response materials.
For these categories, procurement should focus on:
- Correct specifications
- Supplier reliability
- Certificates
- Safety Data Sheets
- Product traceability
- Inspection records
- Clear delivery scope
- Written approval for substitutes
This helps protect the ship manager if a later incident needs to be reviewed by insurers, lawyers or P&I correspondents.
H&M Coverage and Hull/Equipment Procurement Decisions
H&M is often associated with the physical condition of the vessel. Procurement teams do not usually manage H&M policies directly, but their decisions can affect repair quality, claim clarity and recoverability.
Critical Equipment Purchases
When buying equipment connected to hull, machinery or vessel operation, procurement teams should treat technical accuracy as a priority. A cheaper alternative can create serious problems if it is not compatible with the vessel or not accepted by the technical team.
For high-risk items, buyers should confirm:
- Maker and model
- Part number
- Serial number where relevant
- Technical specification
- Class requirement
- Installation requirement
- Warranty terms
- Certificate requirement
- Delivery deadline
- Substitute approval
This is especially important for machinery parts, safety-critical systems and equipment that may later become part of a damage or repair claim.
Repair Materials and Claim Files
When a vessel has suffered damage, procurement may need to source parts or materials for repair. In that case, the purchasing trail can become part of the claim file.
Useful documents may include:
- Original requisition
- Technical superintendent approval
- Supplier quotation
- Purchase order
- Delivery note
- Invoice
- Photos before and after delivery
- Certificate or test report
- Repair report
- Installation record
- Correspondence with supplier
If procurement records are incomplete, it can become harder to explain what was purchased, why it was selected and whether the cost was reasonable.
Warranty and Insurance Are Not the Same
Warranty and insurance are often confused. A warranty usually relates to the supplier’s or manufacturer’s responsibility for product quality or defects. Insurance relates to covered risks under a policy.
For example, if a part fails because of a manufacturing defect, warranty may be relevant. If the part is damaged during an insured event, insurance may be relevant. If the part was incorrectly specified or installed, neither route may be straightforward.
Procurement teams should keep warranty terms, supplier liability and insurance assumptions separate.
Supplier Liability and Indemnity Clauses
Supplier liability is one of the most important procurement topics in marine supply. Insurance may support risk transfer, but the contract still needs clear wording.
A supplier liability clause defines what the supplier may be responsible for if something goes wrong. An indemnity clause may require one party to protect the other from certain losses, claims or liabilities.
Why Liability Clauses Matter
Marine supply involves time pressure, operational complexity and high-value assets. A small delivery issue can create large consequences if it delays a vessel, causes re-delivery, damages equipment or results in third-party claims.
Procurement teams should review supplier terms for:
- Product liability
- Delivery liability
- Late delivery consequences
- Damage during transit
- Incorrect product supply
- Substitute approval
- Limitation of liability
- Indemnity wording
- Insurance requirements
- Governing law
- Dispute handling
A low-cost supplier with weak liability terms can create a higher long-term risk.
Insurance Certificates and Supplier Vetting
For critical suppliers, procurement teams may request evidence of relevant insurance. This may include public liability, product liability, professional liability, cargo insurance or other coverage depending on the service type.
The goal is not only to collect a certificate. Buyers should also check whether the insurance is relevant to the supplier’s actual scope.
Useful checks include:
- Name of insured party
- Policy period
- Coverage type
- Coverage limit
- Territory
- Exclusions
- Scope of activities
- Certificate validity
- Whether subcontractors are included
This is especially important for technical suppliers, logistics providers, service vendors and high-risk product categories.
Cargo Insurance for Marine Spare Parts in Transit
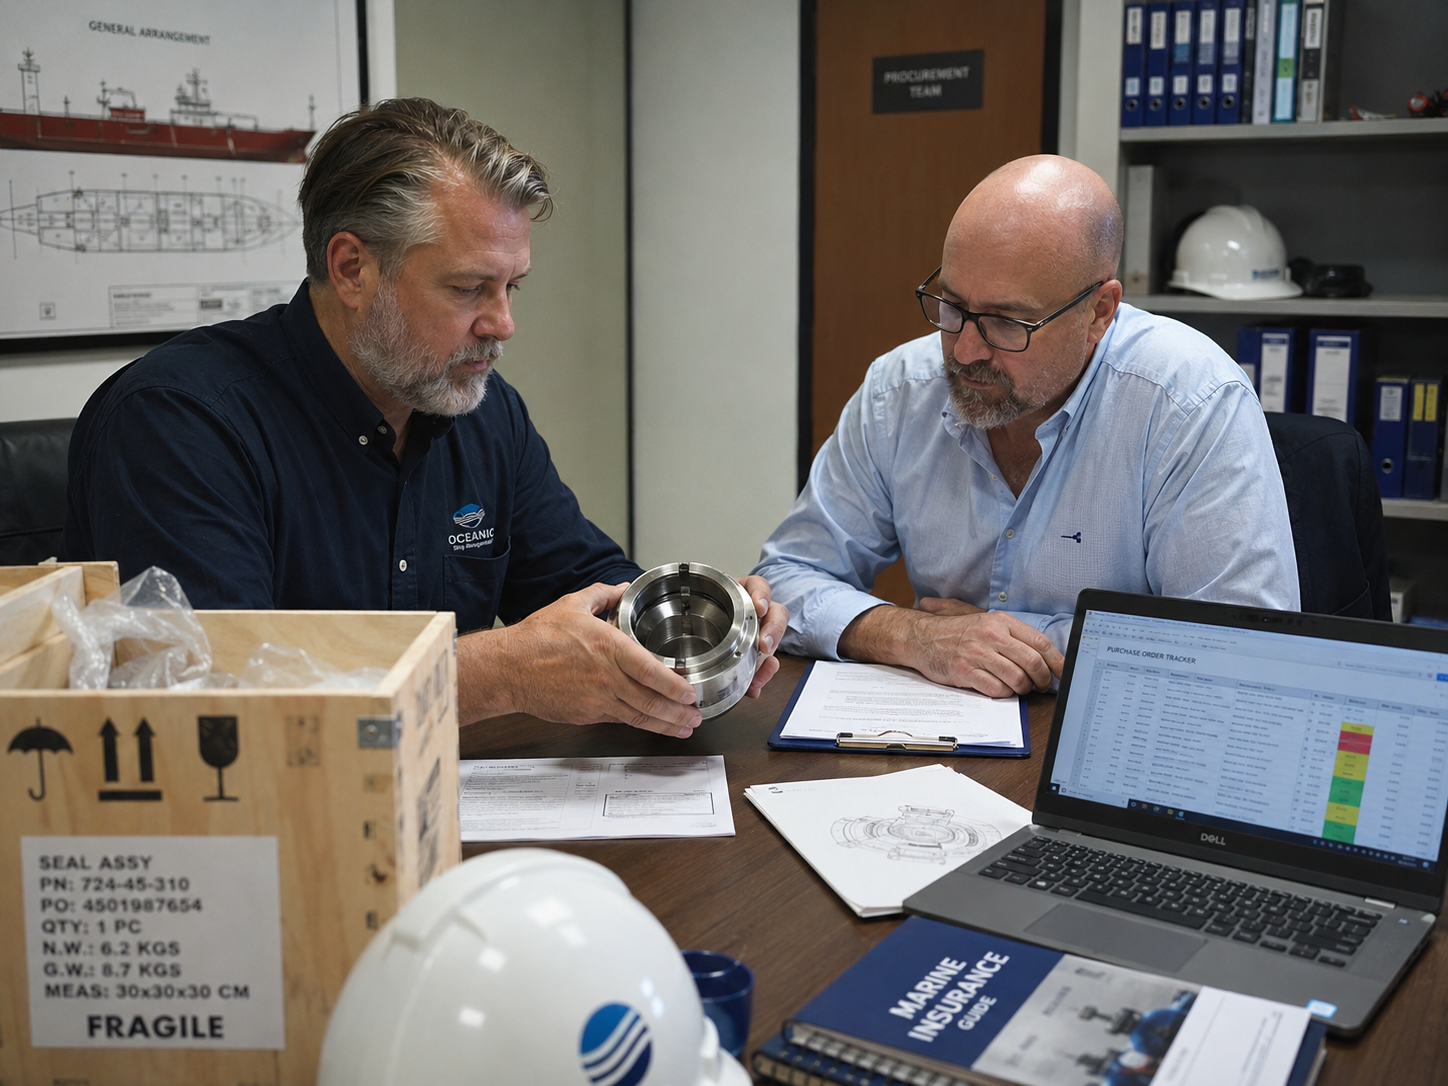
Marine procurement often involves moving spare parts across countries, airports, seaports, warehouses, agents and vessels. Each movement creates risk.
A spare part may be damaged, delayed, lost, stolen, mishandled or held at customs. If the part is urgent, the financial loss may be more than the item value because the vessel may miss a repair window or need a next-port solution.
Who Is Responsible During Transit?
Responsibility depends on the contract, Incoterms, purchase order terms, freight arrangement and insurance setup. Procurement teams should clarify this before shipment, not after damage occurs.
Key questions include:
- Who arranges freight?
- Who pays for freight?
- Who insures the goods?
- When does risk transfer?
- Is the supplier responsible until delivery onboard?
- Is delivery to agent considered completed delivery?
- Are air freight, sea freight and inland transport covered?
- What happens if the part is damaged before reaching the vessel?
- What documents are needed for a transit claim?
Clear answers reduce disputes when something goes wrong.
High-Value and Urgent Spare Parts
High-value and urgent spare parts need stronger logistics and insurance control. Buyers should avoid vague shipping instructions when the part is expensive, fragile or time-critical.
Good practice may include:
- Clear packing instructions
- Photo before dispatch
- Insurance confirmation
- Tracking details
- Freight forwarder contact
- Delivery deadline
- Customs documents
- Serial number record
- Condition report on arrival
- Immediate damage notification process
For urgent ship supply, speed matters, but speed without documentation can create claim problems later.
Claims Handling and Documentation Trail
Insurance-related procurement issues are often decided by documentation. A buyer may have acted correctly, but without a clear record, it becomes difficult to prove what happened.
The documentation trail should show the full story from request to delivery and, if needed, from damage discovery to claim closure.
Core Claim Documents
The exact documents depend on the incident, policy and contract. However, procurement teams should usually be ready to provide:
- Requisition
- RFQ
- Supplier quotation
- Purchase order
- Invoice
- Packing list
- Delivery note
- Bill of lading, airway bill or courier record
- Photos of goods before dispatch
- Photos of damage
- Onboard receipt
- Certificate or test report
- Warranty document
- Email correspondence
- Survey report if applicable
- Complaint record
- Credit note or replacement record
The earlier these documents are collected, the easier the claim process becomes.
Internal Communication
Procurement should not handle claims in isolation. Insurance-sensitive issues may require input from technical, operations, legal, finance, HSQE, the vessel team and insurers.
A good internal escalation process helps define:
- What happened
- When it happened
- Where it happened
- Who had custody of the goods
- What was damaged
- Whether the vessel was affected
- Whether there was third-party exposure
- What immediate action was taken
- What documents are available
This protects both the procurement team and the wider ship management organization.
How AVS Supports Procurement Risk Control
AVS Global Ship Supply & Catering supports procurement teams by coordinating vessel supply requirements, clarifying product details, sourcing suitable items, supporting documentation needs and aligning delivery planning with vessel schedules across international ports.
For ship supply, provisions, technical stores, bonded stores or urgent vessel requirements, use Quick Quote.
For related technical governance topics, see The Role of Classification in Modern Shipping.
Conclusion: Insurance-Aware Procurement Reduces Operational Risk
Marine insurance does not remove procurement risk. It makes documentation, supplier selection, liability terms and delivery control even more important.
Procurement teams that understand the basics of P&I, H&M and cargo insurance can make better supply decisions, ask stronger questions and protect the organization when claims arise.
The safest approach is to combine commercial discipline with operational awareness: clear RFQs, reliable suppliers, accurate PO terms, proper certificates, strong delivery records and early escalation when something goes wrong.
AVS supports marine procurement teams with global ship supply, provisions, technical stores, bonded stores and coordinated vessel supply solutions across international ports.
For procurement support and vessel supply requests, use Quick Quote.
FAQ
What is a P&I club?
A P&I club is a mutual marine insurance association that provides liability cover for shipowners and operators. P&I is commonly connected to third-party liabilities such as crew, pollution, cargo-related liabilities and operational incidents, depending on the club rules and case details.
Are spare parts in transit covered by H&M?
Not always. H&M usually relates to the vessel’s hull, machinery and installed equipment. Spare parts in transit may require cargo insurance or a separate transit arrangement, depending on the policy, contract terms and point of risk transfer.
Who pays if a spare part is damaged en route?
Responsibility depends on the purchase contract, Incoterms, freight arrangement, insurance terms and when risk transfers from seller to buyer. Procurement teams should clarify this before shipment.
What is the role of cargo insurance for ship supply?
Cargo insurance helps protect goods against loss or damage while in transit. For ship supply, it is especially important for high-value spare parts, urgent technical items, international shipments and multi-leg logistics.
How do P&I clubs affect provisions procurement?
P&I may become relevant if provisions create crew health, welfare or liability issues. Procurement teams should focus on food safety, supplier reliability, shelf life, cold chain control and delivery documentation.
Does AVS hold liability insurance?
Procurement teams should request current insurance certificates, liability details and contractual documentation directly during supplier onboarding or RFQ discussions. Coverage should always be verified based on the current contract, service scope and applicable terms.
What is an indemnity clause in a marine supply contract?
An indemnity clause is a contract provision where one party agrees to protect the other from certain losses, claims or liabilities. In marine supply, it can relate to product failure, delivery issues, third-party claims or supplier-caused damage, depending on the wording.
How does insurance affect supplier selection?
Insurance affects supplier selection by showing whether a supplier has appropriate risk controls and financial protection for its scope. Buyers may review insurance certificates, liability limits, policy validity, exclusions and relevance to the supplied goods or services.
What documentation is needed for a claim?
Common claim documents include requisitions, RFQs, quotations, purchase orders, invoices, delivery notes, packing lists, transport documents, photos, certificates, correspondence, onboard receipt and survey reports where applicable.
How do warranty and insurance interact?
Warranty and insurance are different. Warranty usually relates to product quality or defects, while insurance relates to covered risks under a policy. A failed part may involve warranty, insurance or neither depending on the facts.
Are crew welfare expenses covered by P&I?
Some crew-related expenses may fall under P&I depending on the club rules, policy terms and circumstances. Procurement teams should not assume automatic coverage and should keep clear records for medical, welfare or provisions-related issues.
How do mooring rope failures interact with insurance?
Mooring rope failures may involve several areas: product quality, maintenance, onboard use, third-party damage, injury, port damage, P&I exposure or H&M-related consequences. Procurement records, certificates, inspection history and incident details are critical for review.